
Logistics and Planning: What Sellers Overlook Before Listing
Timing and planning decide how smoothly the sale goes. These five items are easy to overlook until they cause a problem.
Timing and planning decide how smoothly the sale goes. These five items are easy to overlook until they cause a problem.
Show-readiness and access
Why it matters: Showings come with little notice. A home that takes hours to get ready, or that is hard to enter, gets fewer showings, which shrinks the pool of buyers.
What to do:
- Decide how quickly the home can be ready to show, and plan for pets, children and work-from-home schedules.
- Find the cause of any access problem, such as tenants, locked rooms, gates or alarm codes, and settle it with your agent: lockbox access, notice periods, and how access works if there are tenants or other occupants. Set showing windows with your agent.
What not to do:
- Do not limit showing times so much that buyers cannot see the home.
- Do not stay home during showings.
- Do not leave pets loose, or valuables and medications out.
- With tenants, follow the lease and the law.
- Ask your agent about anything else that applies.
Where you will live and store things
Why it matters: A sale takes weeks to months, and living in a home that is being shown is hard. Planning avoids a rush that leads to clutter, damage or extra costs.
What to do:
- Decide whether you will stay or move out first, and when.
- Sort belongings before packing and choose storage (a rented unit, a portable container or a family garage).
- Pack and label off-season and nonessential items first.
- Keep essentials within reach.
- Plan where you will go if the timing of your sale or your purchase shifts.
What not to do:
- Do not crowd the garage, attic or crawl space with storage while the home is listed, since buyers and inspectors need to see and access them.
- Do not leave the decision about where to live until after you have an offer.
- Do not leave a home vacant without checking your insurance coverage.
Contractor lead times
Tradespeople are not always available on short notice, and repairs found late can delay your sale. Lead times vary, so allow for them when you plan your timeline, and get written estimates, licenses and receipts for any work.
An outside opinion
Why it matters: You stop seeing problems you live with. An outside view shows what buyers will notice and in what order to address it.
What to do:
- Ask an agent for a walk-through before you start any work, and ask a friend with fresh eyes as well.
- Ask what is most likely to come up at the inspection and what to fix first, and take notes.
- Consider a pre-listing inspection to find the causes of problems before a buyer's inspector does.
What not to do:
- Do not take comments personally; the goal is to see what a buyer will see.
- Do not start projects before the walk-through.
- Do not rely only on people who are used to the home.
Avoiding over-improving
Some updates cost more than they return, and the money comes out of your proceeds. Start with condition, then appeal, ask your agent what comparable homes sold for before any large project, and do not start a kitchen or bath remodel just before listing without that input: [link: return on investment post].
See the full guide: What Do Sellers Overlook Before Listing? A Short Guide
If something turns up, we can help
As agents we work with contractors and other vendors regularly, and we can share names from our experience and help you compare bids. You always choose who to hire. A broker should not require you to use their vendor, and should not be paid by a vendor you hire.
From Our Own Experience
As agents for buyers and sellers, we see both sides of transactions. Here are a few issues we’ve encountered that could easily have been avoided.
- As we were about to go to market, we had a final walkthrough with the seller. They did a great job of cleaning out the home, but put all of the boxes in the garage. This wasn’t the problem though: About 20 of those boxes were stacked in front of the furnace, water heater, and electric panel making it nearly impossible for the inspector to access them without a lot of work. An inspector who goes to that much trouble to access those items will probably make sure to find something to note in the report.
- The vendor who installed new carpet covered the crawl space access. Five minutes with a carpet knife during installation would have saved a lot of time searching for the access panel.
- A secondary electric panel that was hidden behind loose boards. The inspector knew there was a secondary panel when inspecting the primary, but could not find it.
- An older home that had a newer electrical panel, but two sets of outlets close to each other. The expectation was that one set was the original and decommissioned (but not removed/capped), and the other was the newer service. However, the buyer’s inspector had to test all of the outlets and report that some did not work or were ungrounded, raising inspection items and additional questions during the inspection response period.
A list of changes or improvements with the dates and locations if necessary, and permits or information about the licensed vendor come in handy when questions arise.
Thinking about buying or selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
Paperwork and Records: What Sellers Overlook Before Listing
Many sellers leave paperwork until the last minute. Organized records support your price and keep the sale on schedule.
Many homeowners leave finding and organizing their paperwork and records until the last minute. Then they have to scramble for the information, or never get to it before the home goes on the market.
Organized records are valuable in three ways:
- They identify changes and maintenance. Maintenance records can make a buyer more comfortable with the purchase, and improvements and major upgrades can add value through warranties and design information.
- They help market the home by showing what was done and when. Most buyers do not need to know the cost of the work, but the list shows the home was cared for.
- When your home sells, there will be an accounting for tax purposes. Organized records make it easier to document for your accountant, and may save you money.
Service records and receipts
Why it matters: Buyers and inspectors want to know whether major systems have been maintained. Records show what was done, when and by whom. Having this information ready for potential buyers helps support your price.
What to do:
- Start with a list of major systems and work: furnace or HVAC, water heater, roof, sewer, windows and remodels.
- Find the records: emailed receipts, bank or card statements, contractor invoices, permits and warranties. Ask contractors for copies if you do not have them.
- Keep one folder, on paper or digital, with the date, what was done, who did it and the cost. Records of major improvements may matter for tax purposes when you sell, so ask your CPA which ones to keep.
What not to do:
- Do not guess or round dates.
- Do not share receipts that show account numbers or other personal information.
- Do not wait until the last minute.
Documents to gather
Why it matters: HOA documents, warranties, manuals, utility history and earlier inspection reports answer buyer questions before they are asked. Documents held by an association can take time to obtain, and missing ones can delay a sale.
What to do:
- List what applies: HOA or condo documents and fees, warranties, appliance manuals, twelve months of utility costs, earlier inspection reports and repair records.
- Find who holds each item (the HOA manager, a builder, a utility account) and request them early. Put everything in one place and tell your agent what you have.
What not to do:
- Do not hold back an earlier inspection report without asking your agent how it affects your disclosures.
- Do not promise that a warranty transfers until you have read its terms.
- Do not wait for the buyer to ask.
Permits
Unpermitted work can come up when a buyer's agent, inspector, appraiser, lender or insurer asks, and it can stall a closing. Check the permit records for your address and do not leave unpermitted work out of your disclosures: [link: unpermitted work post].
See the full guide: What Do Sellers Overlook Before Listing? A Short Guide
From Our Own Experience
In 2025 we helped a buyer purchase an old, charming home. That home had an addition at some point (adding two bedrooms), but no one knew when that was added.
After the purchase and closing, the buyer contacted the city to have recent changes and upgrades inspected so there would be no issue when they eventually sell the house.
They were getting ahead of something that they knew would make most buyers more comfortable.
During that process the city inspector noted that he could not find building plans on file, so he questioned whether the addition had been permitted correctly.
Our buyer (and now homeowner) had no information from the seller on when it might have been done. However, the seller had left behind a collection of photos, some dated decades earlier, that showed the addition being built. They helped the city narrow its search for the documents.
Thinking about buying or selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
Tax: Tax treatment depends on your individual circumstances and changes over time. Consult a CPA or tax professional about your situation.
Presentation: What Sellers Overlook Before Listing
There are things we see every day and no longer notice: odors, dust, burned-out bulbs. Buyers notice them right away, and they are easy to fix.
There are things that are present every day, but we just don’t notice them anymore. Odors. Dust. Mismatched or missing light bulbs. These all make an impression on potential buyers, and are easy to fix.
Remember that buyers usually see the home online before they visit, so the first impression happens on a screen, and that screen is often on a phone, not a computer. If they don’t like what they see in the pictures, they won’t be interested in touring the home.
And even if the pictures are great, when they enter the home they will be looking to confirm that the photos were “real,” and they will notice things you have become “nose blind” to.
These items help improve how the home looks in photos and at showings.
Lighting
Why it matters: Lighting changes how every room looks in showings and photos. Mismatched or dim bulbs make rooms look dated, and a dark home at a showing is a poor experience, especially when a buyer cannot find a switch.
What to do:
- Check every fixture, lamp and switch. Replace burned-out or flickering bulbs, and if a fixture keeps failing, find out why (a loose connection, or a dimmer that does not work with the bulb).
- Use matching bulbs in each room, with the same brightness and color. Many big box home improvement stores now sell LED bulbs that can be switched between brightness and color settings, which makes matching easier.
- If you use home automation to manage your lighting, review the scenes and routines you have set. A buyer who enters a dark home and cannot turn on the lights has a poor experience. Set the lights to be on, or make sure the switches work normally. Open curtains and blinds for showings and photos. It also helps to mention the home automation in the listing, even if you do not describe every feature.
What not to do:
- Do not leave lighting on a routine that turns lights off or dims them during showings.
- Do not mix warm and cool bulbs in the same room.
- Do not exceed a fixture's wattage rating.
The professional-photo test
Why it matters: Photos show clutter, harsh light and dark corners that are easy to miss in person.
What to do:
- Take phone photos of each room from the doorway and from corners, the way a photographer would.
- Look for clutter, cords, reflections, dark corners and personal items.
- Find the cause of each problem you see (a dark corner may need a lamp or a brighter bulb, and clutter needs to go), fix it, and retake the photo.
- Repeat until the photos need no explanation, then have the photographer shoot.
What not to do:
- Do not rely on how the room looks in person.
- Do not wait until the photographer arrives to fix what you can fix now.
- Do not use editing that misrepresents the home.
Deep cleaning and odors
Buyers notice fingerprints, dusty vents and odors within seconds, and odors make them wonder about mold, pets or smoke. Find the source of any odor, deep clean, and do not cover it with air fresheners: [link: odors post].
Declutter and depersonalize
Clutter makes rooms look smaller and hides condition, and buyers open closets and garages. Clear counters, thin out closets, and keep access open to the attic hatch, electrical panel and water heater: [link: decluttering post].
Neutral paint and flooring
Bold colors and worn floors narrow the pool of buyers. Patch, prime and repaint in a light neutral, check what is under old carpet, and in an older home check for asbestos before sanding or tearing out old flooring: [link: paint post] and [link: hardwood floors post].
Curb appeal
The first impression happens online and again at the curb. Fix causes first (such as drainage that stains walkways), then freshen the entry, trim the beds and use a soft wash on siding: [link: curb appeal post].
See the full guide: What Do Sellers Overlook Before Listing? A Short Guide
From Our Own Experience
We were walking through a home with a seller just before listing their home. They had spent weeks cleaning things and packing away clutter.
While Kelly was talking with her, Kelly looked up at the cold air return vent in the ceiling. It was extremely dirty.
The seller was shocked. She had lived in the home for many years, and didn’t recall having ever noticed that cold air return, much less remembered ever cleaning it.
It was easy to correct, and a potential “poor impression” was avoided.
Thinking about buying or selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
How Are Home Values Doing in Our Area, and Why?
Prices are lower than a year ago, inventory is higher and fewer homes are selling. Here is the data, with dates, and what it means if you are thinking about selling.
As of November 9, 2026: this post uses NWMLS data compiled by InfoSparks (ShowingTime) for median prices, NWMLS monthly reports for August and October 2026, Freddie Mac mortgage rates through November 5, 2026 and NAR data for the third quarter of 2026. Market numbers change often, so contact us for current figures.
This is a very time-sensitive post. While many of the topics here are not specific to the current market, the details are very time-centric and need to be re-analyzed regularly. We highly encourage you to contact us for current market information.
The short answer
Prices in King County are lower than a year ago (down 3.7 percent for houses and 15.9 percent for condos in October), inventory is higher, and fewer homes are selling. National prices have been slightly higher. Here is the data, with dates.
King County
| Measure | August 2026 | October 2026 |
|---|---|---|
| Median sales price | Houses $925,000 (down 5.1% from August 2025) Condos $509,000 (down 7.5%) | Houses $938,863 (down 3.7% from October 2025) Condos $470,700 (down 15.9%) |
| Active listings | 7,703 (up 30.0% from a year earlier) | 7,592 (up 32.8%) |
| Closed sales | 1,791 (down 13.6%) | 1,756 (down 18.1%) |
| Pending sales | 2,101 (down 8.4%) | 1,831 (down 17.8%) |
| Months of inventory | 4.30 | 4.32 |
The ten-year view
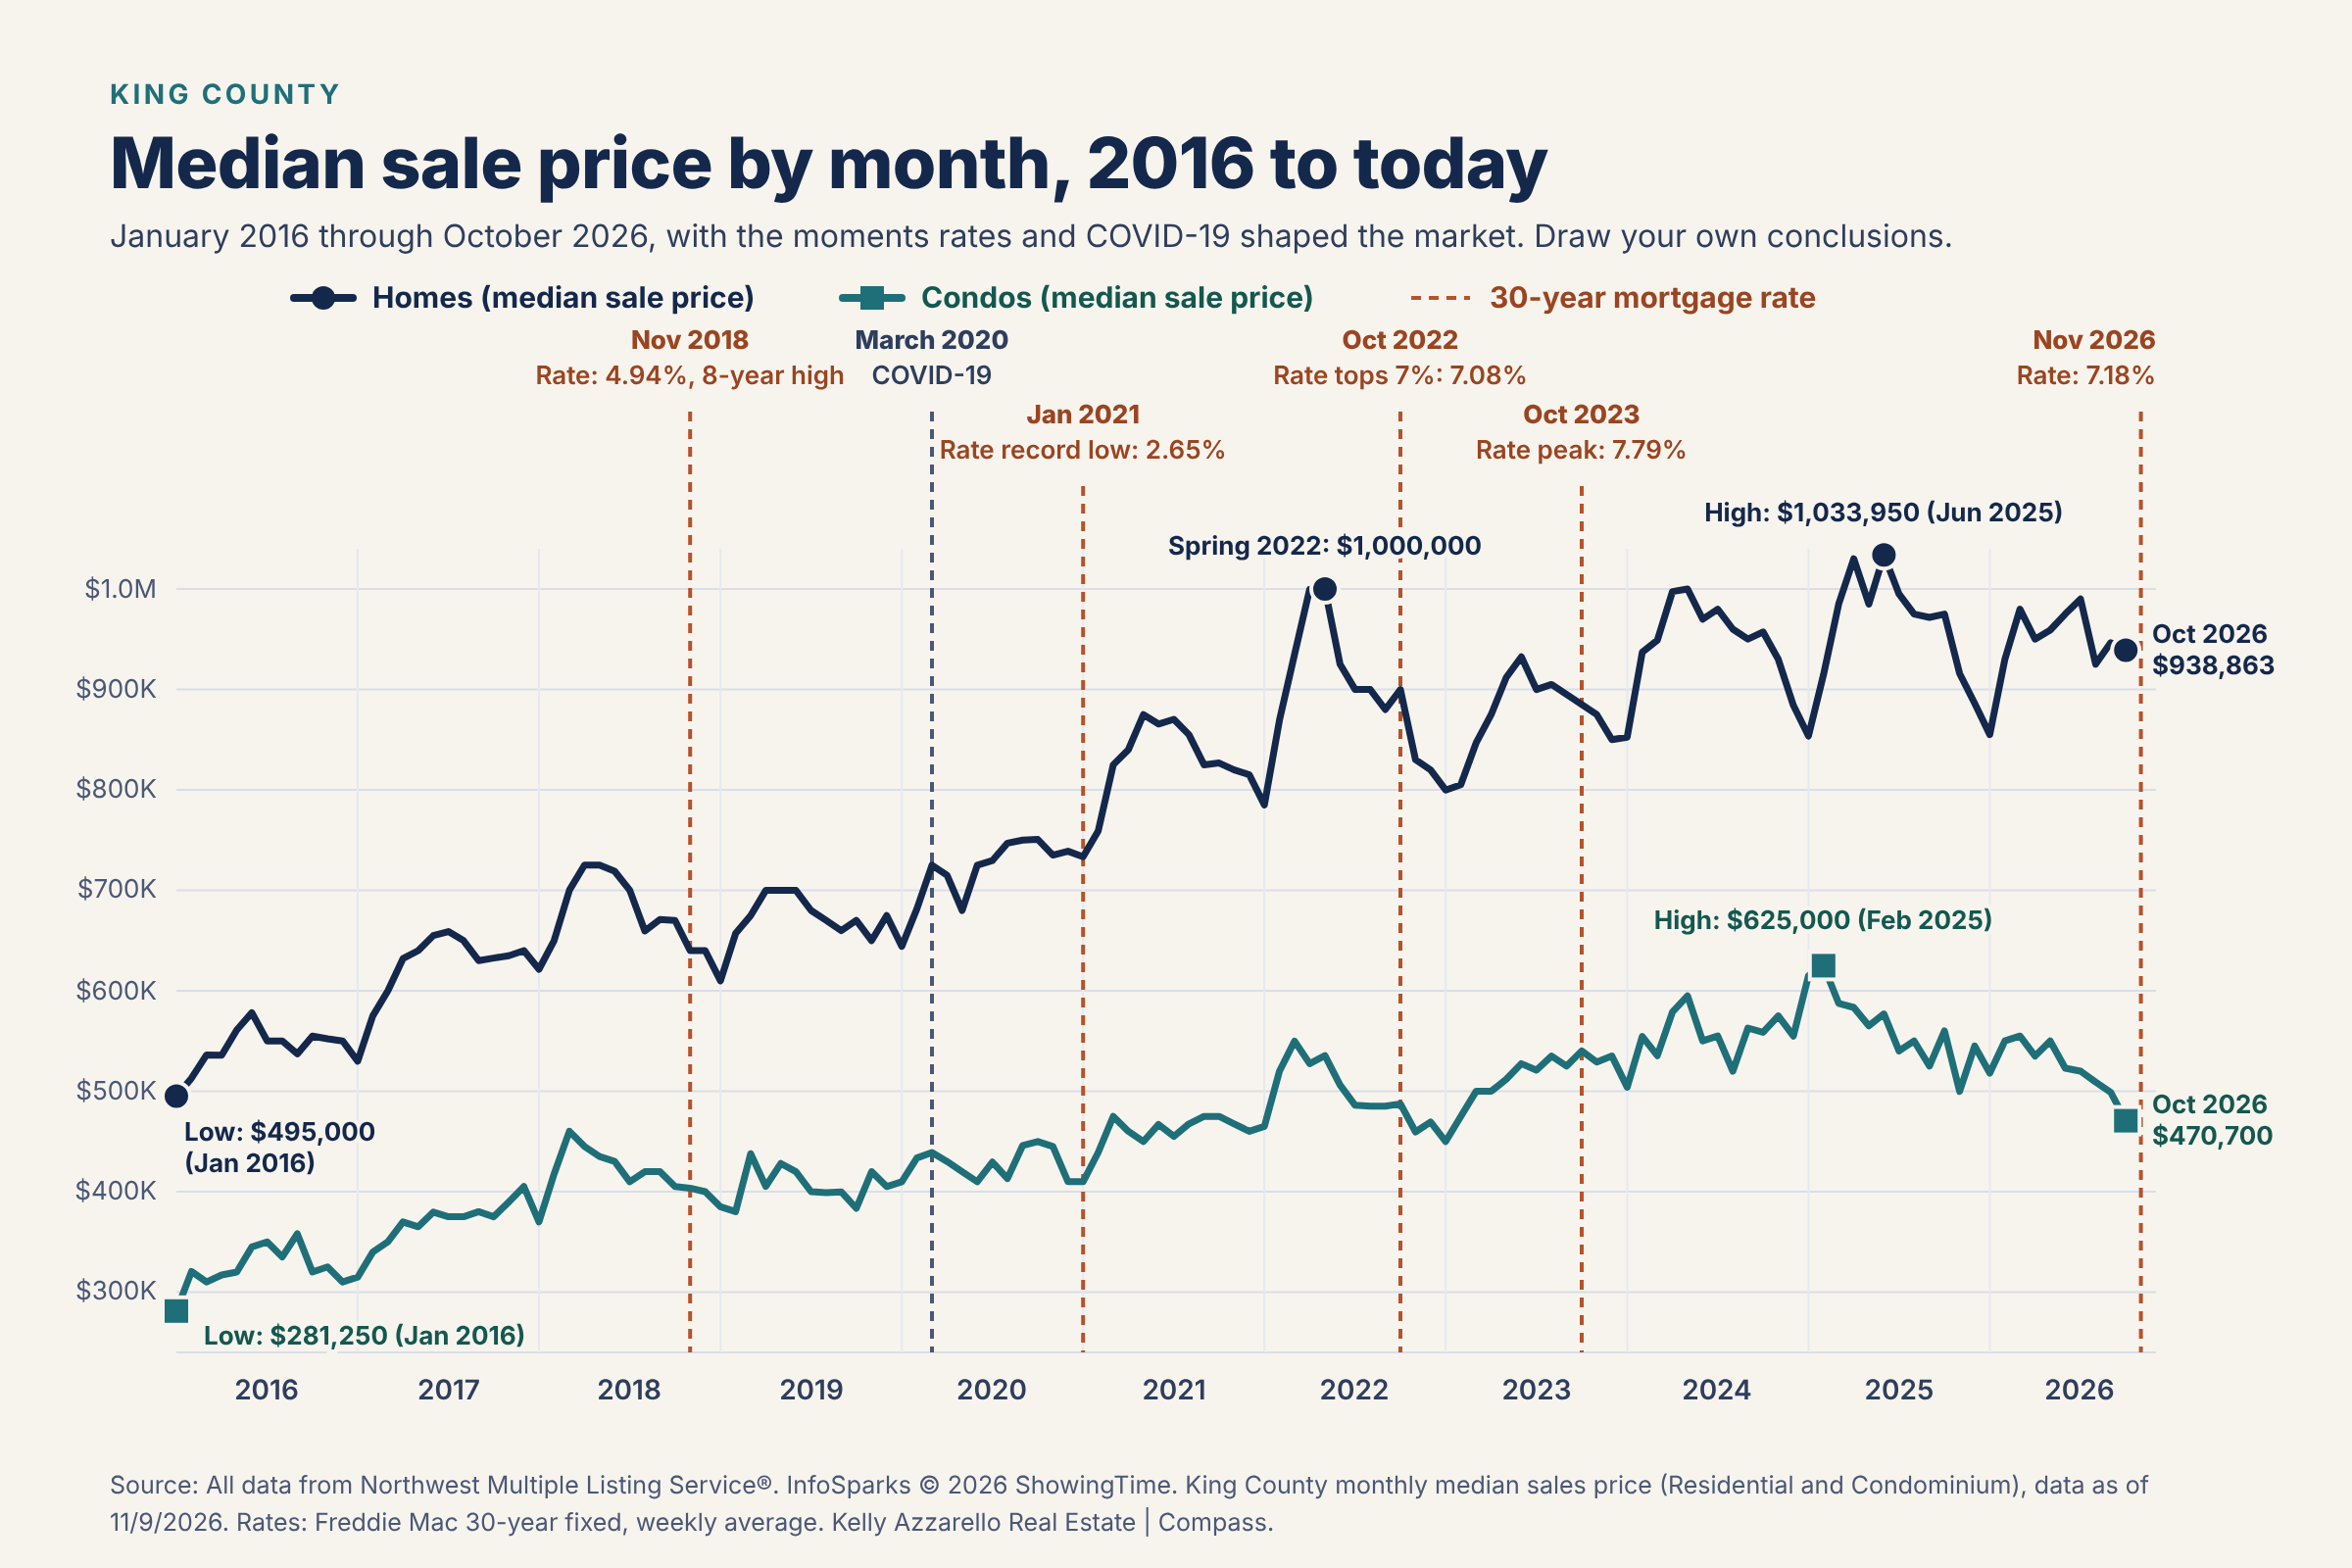
Using Northwest Multiple Listing Service data compiled by InfoSparks (ShowingTime), the King County median sale price for houses peaked at $1,033,950 in June 2025 and was $938,863 in October 2026. For condominiums, the peak was $625,000 in February 2025 and the October 2026 median was $470,700. The lows in this ten-year period were $495,000 for houses and $281,250 for condominiums, both in January 2016.
Source: Northwest Multiple Listing Service, InfoSparks © 2026 ShowingTime, data as of November 9, 2026. Mortgage rates: Freddie Mac.
The Eastside
- In the October 2026 NWMLS report, the Eastside median price for single-family homes was $1.35 million, down 12.9 percent from a year earlier (June 2026: almost $1.6 million, down 3.1 percent).
- In October, the most expensive Eastside submarket, Bellevue west of Interstate 405, had a median of a little more than $3.4 million, up 5.4 percent on only 16 sales (in June it was almost $3.7 million, down 19.8 percent). Small, high-priced markets swing a lot from month to month. Median prices in this area are normally skewed high because of the number of very expensive properties.
- King County's median for houses was $938,863 in October 2026, down 3.7 percent from $975,000 in October 2025, and $925,000 in August 2026, down 5.1 percent from $975,000 in August 2025 (NWMLS data compiled by InfoSparks). King County condos had a median of $470,700 in October 2026, down 15.9 percent from $560,000, and $509,000 in August 2026, down 7.5 percent from $550,000 (InfoSparks). The NWMLS October recap showed about 7.0 months of inventory for condos.
How this compares with the country
NAR reported that the national median existing single-family price was $432,900 in the third quarter of 2026, up 1.7 percent from a year earlier. Our area is running below that trend.
Why it is happening
- Affordability. The Washington Center for Real Estate Research said in the NWMLS October report that interest rates rose even further, with 30-year mortgage rates averaging 7.33 percent in October versus 6.86 percent in September. Rates were 5.98 percent at the end of February 2026, the lowest since September 2022, but they have since risen. Freddie Mac's weekly 30-year fixed average was 7.18 percent on November 5, 2026, its third straight weekly decline from 7.40 percent on October 8 and October 15. That is still up from 6.95 percent on September 17, 6.65 percent on August 20 and 6.22 percent a year earlier.
- More supply. King County had 7,592 active listings at the end of October, up 32.8 percent from a year earlier, which gives buyers more choices and more time to decide.
- Slower sales. In October, King County closed sales were down 18.1 percent and pending sales were down 17.8 percent from a year earlier, which points to cooler demand.
What it means for you
Averages hide a lot. A well-prepared, well-priced home in a strong location can still do well, while a home that is overpriced or in need of work sits. If you are thinking about selling, the useful number is not the county median. It is what comparable homes near you have sold for recently.
City-level numbers
We will cover city specific data in a later post. Stay tuned!
From Our Own Experience
Over the last few years, prices in our market have pulled back. This is somewhat expected, because prices rose so quickly in the early 2020s in response to demand during COVID.
Homes that are priced well continue to sell well. Homes priced on the values of previous years (aspirational pricing) tend to sit longer and often need multiple price reductions before they move.
Buyers have also changed how they behave. They are negotiating harder, which we have not seen in several years, since the market here moved up quickly in the late 2010s. Recent requests include:
- Price adjustments or money back at closing based on inspection results
- Offers far below the listing price
- Seller money applied to interest rate buydowns or closing costs
Many of these requests, especially the inspection requests, are considered “unreasonable” by the other party. Even so, fewer sellers have walked away from deals because of them.
Thinking about selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
Sources
- InfoSparks (ShowingTime), Northwest Multiple Listing Service King County monthly median sales price, Residential and Condominium, data as of November 9, 2026
- NWMLS Recaps, October 2026: nwmls.com/wp-content/uploads/2026/11/Recaps-October2026.pdf
- NWMLS Recaps, August 2026: nwmls.com/wp-content/uploads/2026/09/Recaps-August2026.pdf
- NWMLS Market Snapshot, October 2026 (published November 5, 2026): nwmls.com/market-snapshot-october-2026/
- MyNorthwest coverage of the June 2026 NWMLS report (June Eastside figures): mynorthwest.com/lifestyle/425/real-estate-report-inventory-expanding-sales-prices-lower/4254808
- 425 Business, NWMLS October 2026 report (Eastside figures, mortgage rate comments): 425business.com/news/northwest-multiple-listing-service-october-2026-report/article_61c26012-cee7-4bba-bdd1-df6ce5f0790d.html
- NAR, Home Prices Rise in 78% of Metro Areas in Q3 2026 (October 29, 2026): nar.realtor/newsroom/home-prices-rise-78-percent-metro-areas-q3-2026
- Freddie Mac Primary Mortgage Market Survey, rates through November 5, 2026: freddiemac.com/pmms
What Do I Have to Do, and in What Order, to Sell My Home?
Selling goes from a decision, to preparation, to listing, to an accepted offer, to closing. Here are the ten steps in order, and the best time to bring in an agent.
The short version
Selling goes from a decision, to preparation, to listing, to an accepted offer, to closing. Bring in an agent at the beginning, before you spend money on repairs or decide on timing, because the agent can tell you what is worth doing and in what order.
The key milestones
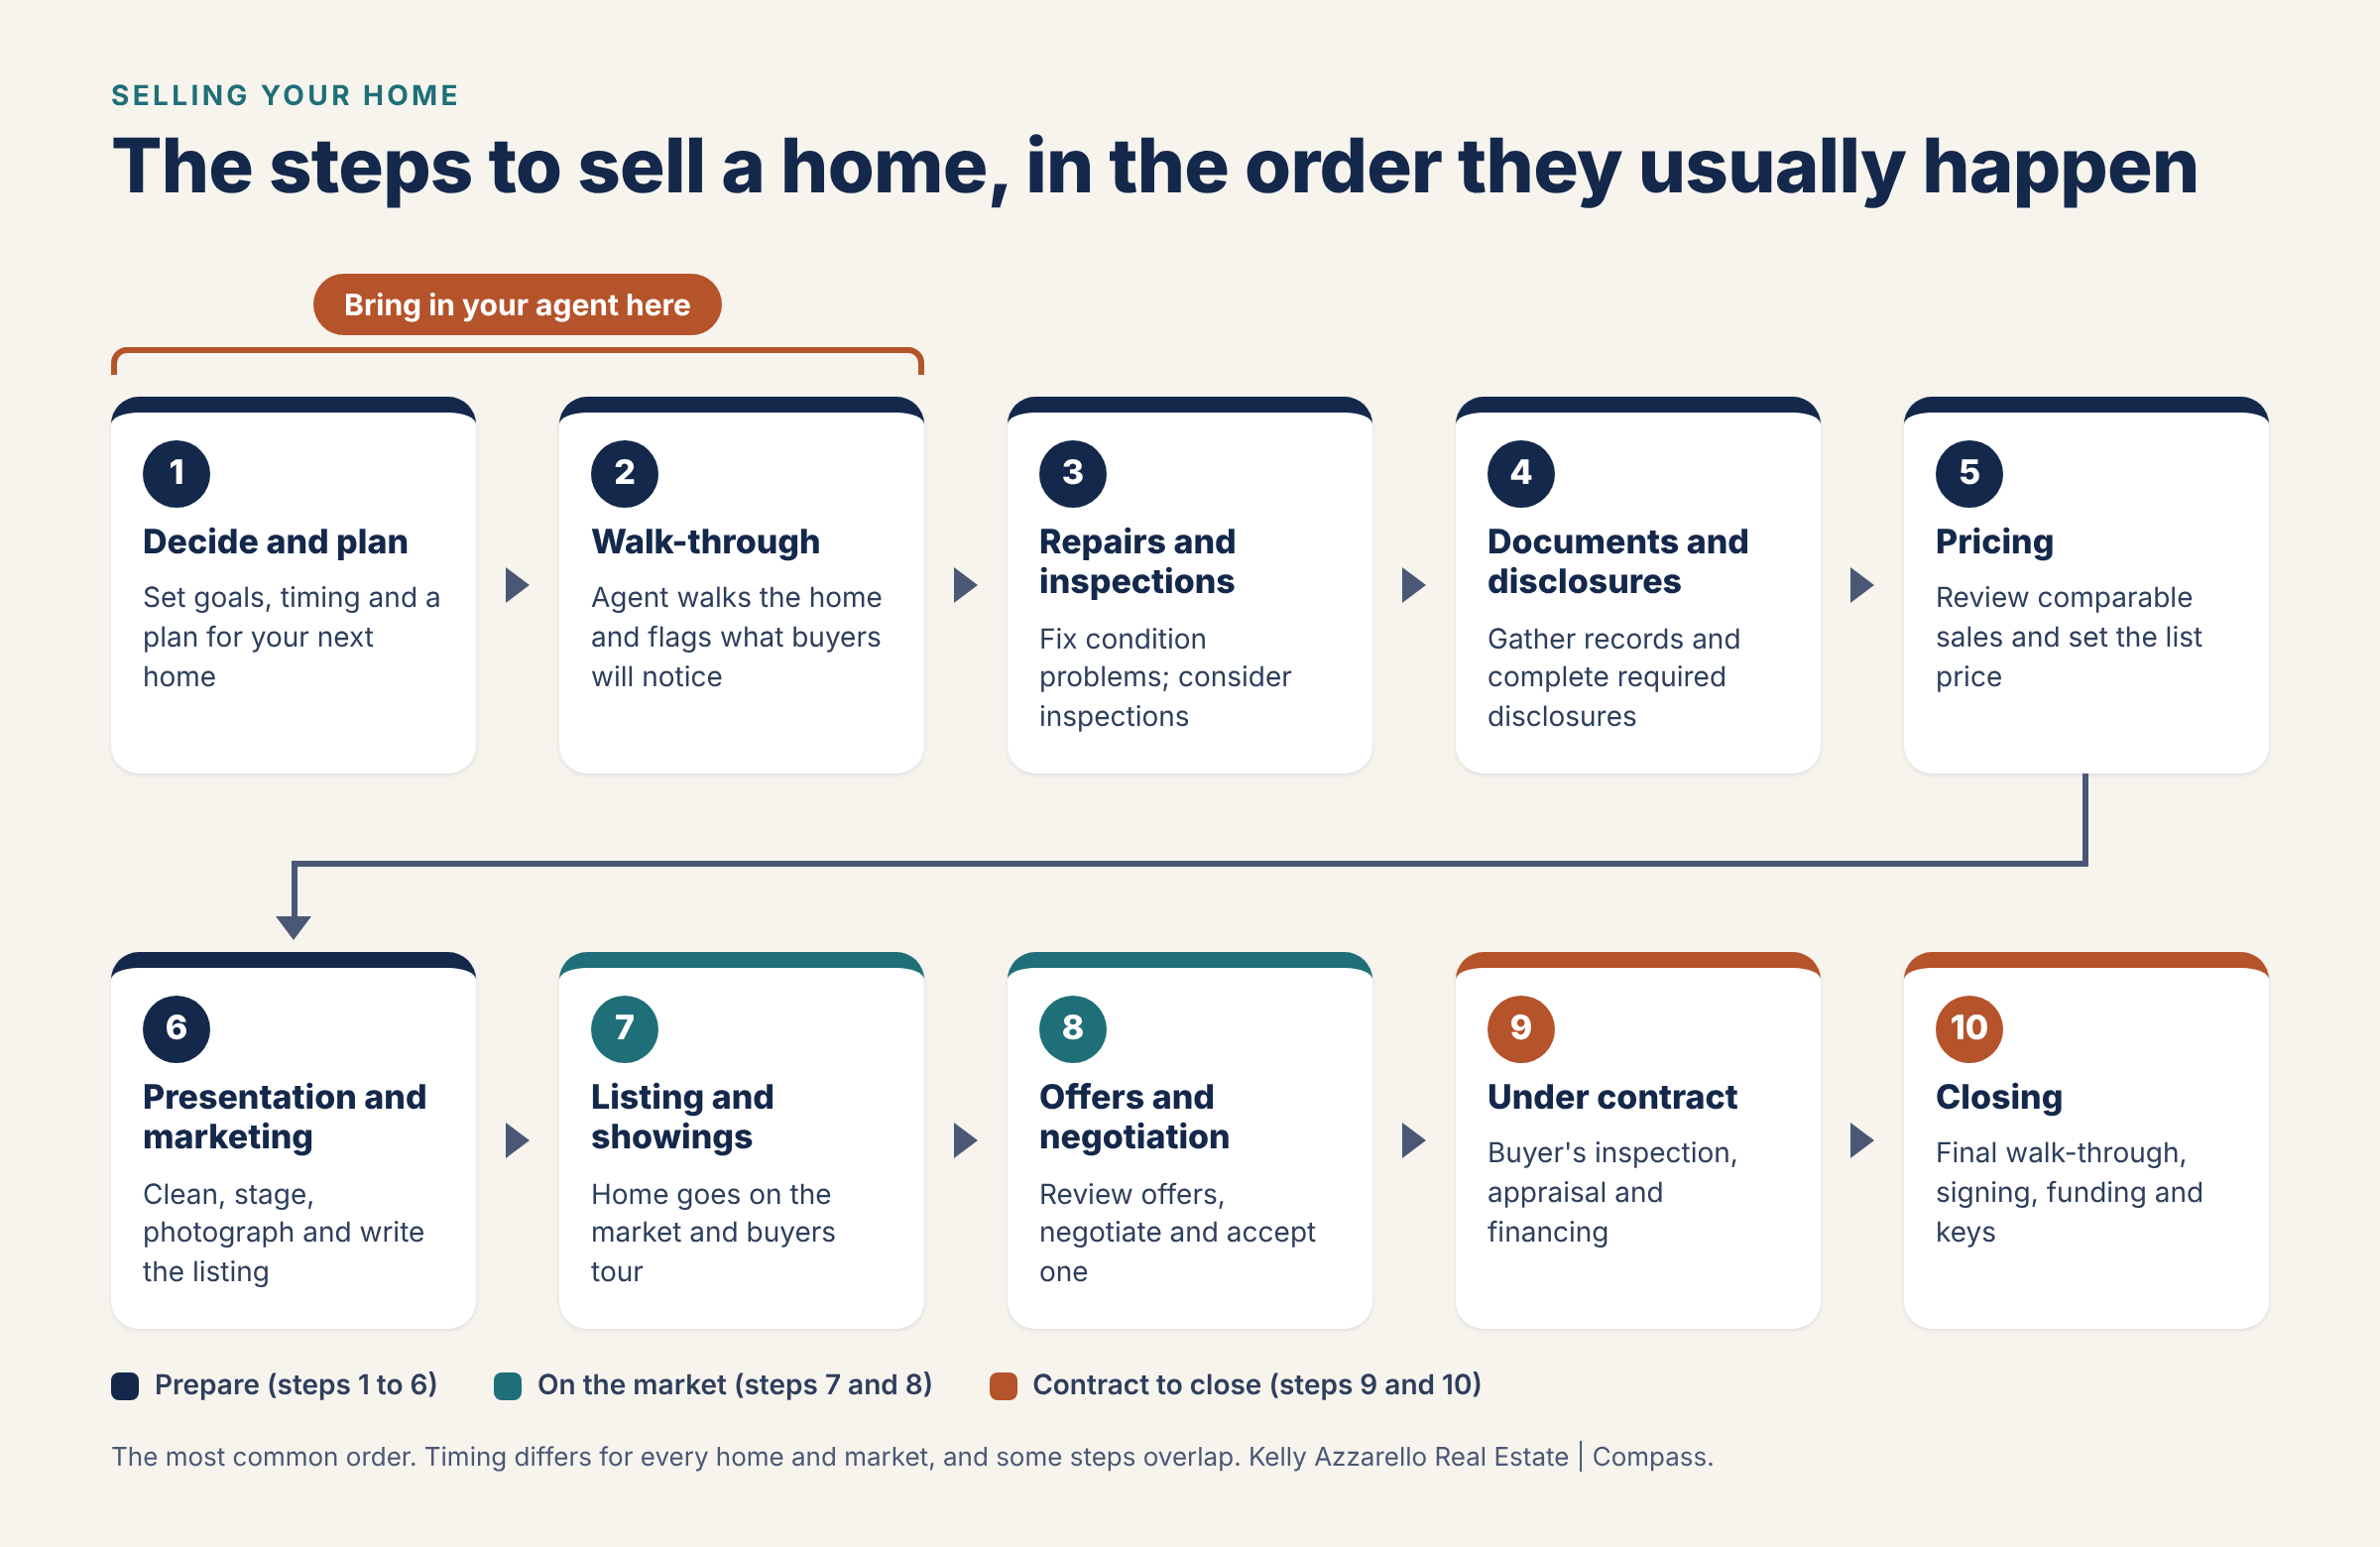
| Step | What happens | Who is involved |
|---|---|---|
| 1. Decide and plan | Set goals, timing, a rough net figure and a plan for your next home | You, agent, CPA, lender |
| 2. Walk-through | Agent walks the home and lists what buyers will notice | You, agent |
| 3. Repairs and inspections | Fix condition problems; consider a pre-listing inspection and specialty inspections | You, contractors, inspectors |
| 4. Documents and disclosures | Gather records, HOA documents and complete required disclosures | You, agent |
| 5. Pricing | Review comparable sales and set a list price | You, agent |
| 6. Presentation and marketing | Clean, stage, photograph, write the listing | You, agent, photographer |
| 7. Listing and showings | Home goes on the market; buyers tour | You, agent |
| 8. Offers and negotiation | Review offers, negotiate price and terms, accept one | You, agent |
| 9. Under contract | Buyer's inspection, appraisal and financing; negotiate repairs or credits | Buyer, you, agents, lender |
| 10. Closing | Final walk-through, signing, funding, handing over keys | You, title and escrow, agents |
When to get an agent involved
At step 1 or 2. An agent can help you decide whether to sell now, what to fix and what to leave, what your home may sell for, and how to time your next move. Getting advice after you have already started major projects is the most common way sellers spend money that does not pay back.
While it is better to have more time to plan and prepare, we have been able to prepare and get a home on the market in less than 14 days.
Common mistakes
- Starting large projects before getting advice.
- Listing before the home is ready, then trying to fix problems while it is on the market.
- Setting a price based on what you need rather than what comparable homes sold for.
- Waiting until the inspection to learn about problems you could have found yourself.
Thinking about selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
What Is My Home Worth, and How Is the Listing Price Set?
Value, list price and sale price are rarely the same number. Here is how an agent builds a price from comparable sales, and how you can help your number.
Value, price and list price are three different things
Value is what a typical buyer would pay for your home in today's market.
List (aka Listing) price is where you and your agent decide to start. It’s what is listed in the MLS and associated sites, and is a critical part of the selling process.
Sale price is what a buyer actually agrees to pay.
Ideally these three are close, but they are almost never the same number. The gap between them depends on pricing strategy and how the market is moving.
Note: You will also hear about an appraised value (a lender's appraiser's opinion, ordered for the buyer's loan) and an assessed value (the county's number for property tax). Both are different from the three numbers above. We explain how they compare in our post, Appraisal, Sale Price, CMA, Comps and Assessed Value: Which Number Is Which?
Where online estimates fit
Automated online estimates from any of the websites out there are only a quick starting point. They do not know your updates, property condition, a recent sale next door that is not yet in their data, or what a view or a lot is really worth.
Treat these as a rough range, not a figure to price from.
How an agent builds a price
An agent prepares a comparative market analysis (CMA), which looks at three groups of homes.
- Recent sales. Similar homes in your area that closed recently. Agents adjust for differences in size, age, lot, condition and features.
- Pending sales. Homes under contract show where buyers are willing to commit right now.
- Active listings. These are your competition, and a stale listing that has not sold tells you what buyers are not willing to pay.
The agent then adjusts for the market's direction: inventory, how long homes take to sell, and how close sales prices are to list prices. For reference, NWMLS reported that single-family homes sold in 2024 closed at 100.2 percent of list price on average (NWMLS 2024 Annual Review). NWMLS also reported 99.6 percent for all of 2025. In the NWMLS local market update for King County, single-family homes closed at 99.6 percent of list price in June 2026, down from 100.5 percent in June 2025, and at 100.2 percent for the first half of 2026 compared with 101.7 percent a year earlier. Condos closed at 98.3 percent in June 2026. (Source: Northwest MLS Local Market Update, King County, June 2026.)
The agent will then make data-supported modifications to the price on some of the key features of the home. Here are three examples:
- If the house next door sold recently but only has a 2-car garage and your home has a 3-car garage, this is where the agent will make an adjustment higher.
- If that same home has a remodeled kitchen, but yours does not, then the adjustment will be lower.
- Now let’s say your home has a primary suite on the first floor, and the home next door has a 2nd floor primary suite, then the agent will likely adjust the price higher again.
All of this leads to having an agent that understands the market, the homes, and the desires of the buyers in the area. An agent who only represents sellers may not understand the buyer’s viewpoint as well and will likely set the initial price (and negotiations) differently.
Do you have a say?
Yes. The listing price is your decision. Your agent recommends a price and explains why. A good conversation covers the comparable sales behind the number, whether to price at, below or above the likely value, how long you can wait, and what you will do if there are no offers in the first few weeks.
What pricing too high or too low can do
- Too high: fewer showings, a listing that sits, price cuts that signal trouble, and often a lower final price than if you had priced right at the start.
- Too low: you may leave money on the table, though a lower price may draw more offers and sometimes a stronger result.
What you can do to help your number
- Gather records of improvements and maintenance.
- Fix condition problems that would pull value down.
- Ask to see the comparable sales and ask why each one was chosen.
Put yourself in the buyer's shoes; while they may have different tastes and needs, you can do a lot to help your home's sale value by providing your agent with additional information on schools, parks, activities, transit options, etc. Keep a running list (use a phone to notate these as they are discussed or thought about).
Note that an appraisal is a different thing. A lender's appraiser values the home for the buyer's loan, usually after you have a contract and before closing.
Related reading: When Should I Sell My Home? | Who Can I Call to Find Out What to Do (and Not Do) Before Selling? | How Are Home Values Doing in Our Area, and Why?
From our experience
We have seen a great run up in home prices in the northwest over the last few years. We are now in a correction, and that’s expected. Home prices ebb and flow over time, especially when other economic indicators are present.
Right now we have a number of clients who want to use "aspirational" pricing because at some point their house may have been worth that price. Unfortunately that isn’t realistic and we need to clearly understand the market today and what may affect the price in the future, not to predict but to be prepared should we need to adjust.
Here are a few things to consider when you’re pricing your home:
- How long can you afford to wait to sell to “get your price”?
- When interest rates are higher, the buyers have to consider lower priced homes. When interest rates were lower, they could afford higher priced homes. The former pushed prices down, the latter pushes prices up.
- The value of your home in any given market is not personal. It is not about the memories you’ve made in that home.
- It’s not what you ‘have to get’ for your home that determines the price.
The truth is that the price your home commands is the value that a buyer sees in your home. Not a neighbor, not two years ago or two years in the future.
It doesn’t happen often, but we sometimes have to part ways with clients. Most of the time it is because they have unrealistic expectations, and while our business is to provide a service to any and all of our clients, we are a business. We won’t sacrifice a client's money for our own purposes, but we also can’t sacrifice our business or our other clients' transactions because someone has unrealistic expectations.
In February we made the decision to walk away from a listing. It was a developer (flipper) who had a price in mind for the home, because he felt he had to get a certain amount of profit from it.
As of November 1, that home was still on the market.
The market sets the price. We can provide info and background to price things well within the current market climate. We cannot predict the price.
Thinking about selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
When Should I Sell My Home?
Is there a best month to sell your home? Here is King County data by month for 2025 and 2026, and the questions that matter more than the calendar.
There are two questions here: Make certain you understand which is being asked.
- The first question is whether you should sell your home. This is a very personal decision and is something you will likely think about over a long period of time. While significant changes in your life (job transfers, family issues or needs, aging) may happen, most of our clients have been considering selling their home for a significant amount of time.
- The second question is the one we’ll address in detail below: “What month or time of year should I sell my home?” There is historical data to support certain months being better for selling (improved sale price, fewer days on market, etc.). There are also times when putting your home on the market is NOT going to provide an optimal result because fewer people are looking for homes.
There is no single best month
People often ask when the market peaks. The better question is when selling works for your life, your finances and your home, and whether the market gives you a fair shot at the price you need. Three groups of factors decide that.
What the data says about timing
Here is what happened month by month in King County, based on Northwest MLS (NWMLS) data for houses and condominiums combined. New listings are homes that came on the market during the month. Pending sales are homes that went under contract. Closed sales are homes that finished the sale. The first three columns are 2025, a full year. The next three are 2026 so far.
Note on the last column: it is the median days on market for King County, from NWMLS data compiled by InfoSparks (ShowingTime), data as of November 9, 2026. The median is the middle home: half were faster and half took longer, so a few very slow homes do not skew it.
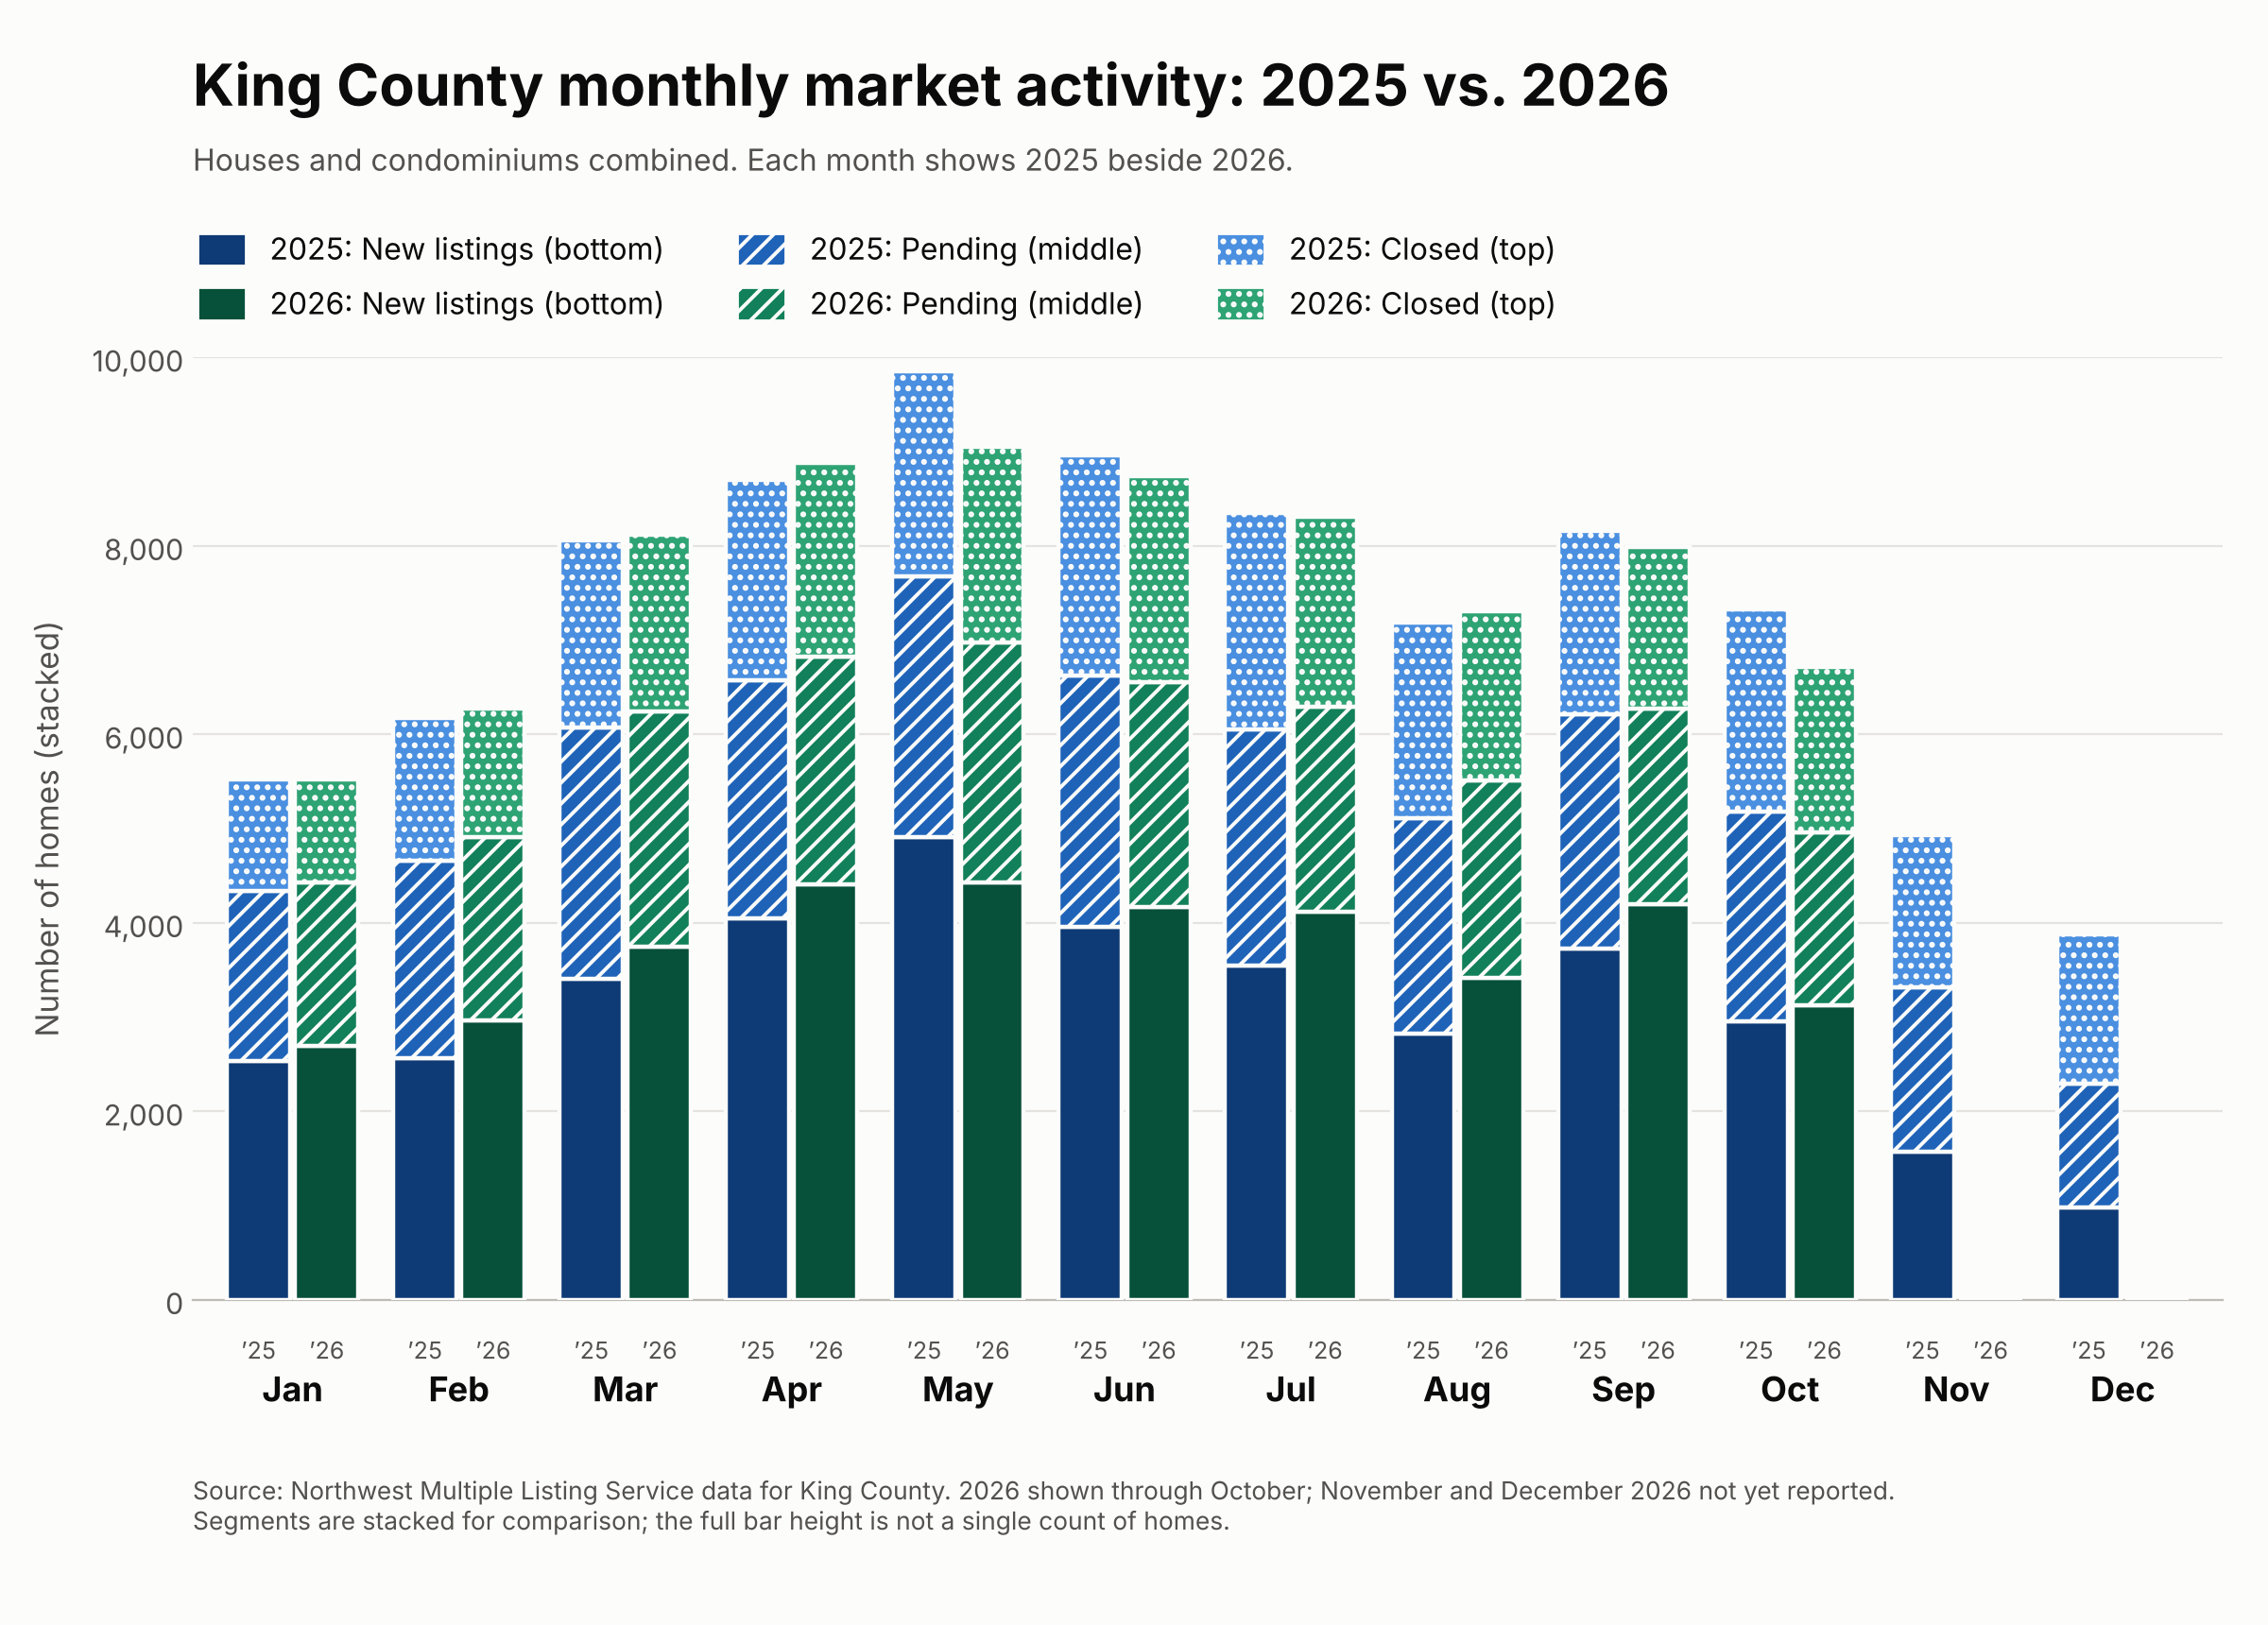
King County, houses and condominiums combined, by month
| Month | New listings 2025 | Pending 2025 | Closed 2025 | New listings 2026 | Pending 2026 | Closed 2026 | Median days on market (2025 / 2026) |
|---|---|---|---|---|---|---|---|
| January | 2,533 | 1,810 | 1,181 | 2,694 | 1,735 | 1,099 | 31 / 42 |
| February | 2,571 | 2,087 | 1,516 | 2,968 | 1,945 | 1,364 | 9 / 16 |
| March | 3,408 | 2,662 | 1,991 | 3,750 | 2,493 | 1,878 | 7 / 10 |
| April | 4,052 | 2,524 | 2,127 | 4,414 | 2,416 | 2,053 | 6 / 10 |
| May | 4,909 | 2,768 | 2,180 | 4,429 | 2,549 | 2,074 | 7 / 10 |
| June | 3,960 | 2,668 | 2,332 | 4,165 | 2,390 | 2,183 | 10 / 13 |
| July | 3,552 | 2,506 | 2,296 | 4,124 | 2,168 | 2,022 | 13 / 15 |
| August | 2,822 | 2,294 | 2,073 | 3,416 | 2,101 | 1,791 | 18 / 20 |
| September | 3,725 | 2,487 | 1,952 | 4,204 | 2,072 | 1,714 | 21 / 22 |
| October | 2,953 | 2,228 | 2,144 | 3,132 | 1,831 | 1,756 | 18 / 18 |
| November | 1,573 | 1,742 | 1,613 | not yet | not yet | not yet | 22 / not yet |
| December | 987 | 1,310 | 1,582 | not yet | not yet | not yet | 31 / not yet |
| January to October total | 34,485 | 24,034 | 19,792 | 37,296 | 21,700 | 17,934 | — |
| 2025 full year total | 37,045 | 27,086 | 22,987 |
What to notice
- Spring is the busiest season on both sides. In 2025, new listings peaked in May (4,909) and pending sales peaked in May (2,768). Closed sales peaked in June (2,332), after contracts written in the spring.
- Winter has far fewer listings, but buyers do not disappear. In November 2025, 1,573 homes were listed and 1,742 went under contract. In December, 987 were listed and 1,310 went under contract. In May, by comparison, 4,909 were listed and 2,768 went under contract. Fewer competing listings does not automatically mean a better price, so the count of listings is only one input.
- So far in 2026 the pattern is different. In every month from January through October, fewer homes went under contract and fewer closed than in the same month of 2025, while new listings were higher in nine of the ten months (May was lower). For January through October combined, new listings were up about 8 percent, pending sales were down about 10 percent and closed sales were down about 9 percent (calculated from the table).
- Homes took longer to sell in 2026. The median days on market was higher than in the same month of 2025 in every month through September, and equal in October (18 days). For example, April was 10 days versus 6, June was 13 versus 10 and August was 20 versus 18. The seasonal pattern shows in both years: the median was shortest in spring (6 to 10 days from March through May) and longest in winter (31 days in December 2025 and 42 in January 2026).
- The data does not point to a single best month. Early in the year provides sellers with less competition as there are few listings and many buyers start their search in the beginning of the year. Spring has the most buyers and the most competing listings. Late fall and winter have fewer of both. Which tradeoff favors you depends on your home, your price and your timeline.
Sources: NWMLS 2025 Annual Statistical Review and Highlights, King County (nwmls.com/wp-content/uploads/2026/01/King-AnnualReview2025.pdf); NWMLS monthly recaps and King County breakouts, January to October 2026 (nwmls.com); InfoSparks (ShowingTime), NWMLS median days on market, King County, data as of November 9, 2026. 2026 figures run through October. November and December 2026 are not yet available.
Some guidelines that will help you make better decisions
Your life
- A job change, retirement, a growing or shrinking household, or a health or care need often sets the date for you.
- Where you will live next, and how long you will need to move, matters as much as the sale itself.
- If you need the proceeds to buy your next home, build in time for both transactions.
Your finances
- Equity. After a sale you pay off your mortgage and selling costs. Ask for a net sheet that shows what you would actually take home.
- Taxes. Generally, if you have owned and lived in the home for a total of 24 months in the five years before the sale, you can exclude up to $250,000 of profit, or $500,000 if married filing jointly. Rules have conditions, so check with a CPA. For the details, see IRS Publication 523.
- Carrying costs. Every month you wait has mortgage, tax, insurance and upkeep costs.
The market
- Inventory and pace. More homes for sale and slower sales give buyers more leverage. See our post, How Are Home Values Doing in Our Area, and Why?, for current numbers.
- Interest rates. Rates affect what buyers can pay. Waiting for a better rate is a bet, not a plan.
- Season. Spring is typically busy, but a well-prepared and well-priced home can sell at other times, and there may be fewer competing listings in off-peak months.
Your home
- A major repair coming up, such as a roof, sewer line or crawl space problem, is better handled before listing than discovered by a buyer.
- If you are not ready to prepare the home, waiting a few months to do it right can pay for itself.
A simple timing check
Ask yourself: When do I need to be out? How long will preparation take? What do I need to net? What are comparable homes doing right now? A walk-through with an agent turns those questions into a plan.
Related reading: What Is My Home Worth, and How Is the Listing Price Set? | I Found a Home I Love for Retirement, but I Don't Know if Mine Will Sell
From Our Own Experience
Trying to time the real estate market is like trying to time the stock market: You’ll never get it exactly right. However, there are times when there are advantages to selling your home. We have had good success with clients who can sell their homes in the early part of the calendar year. We believe that this is due to the following:
- Pent up buyer demand that releases in the new year (after the holidays)
- Buyers who have goals to buy in the new year
- Buyers who wish to take advantage of the fiscal, investment or tax benefits of owning a home (holiday gatherings and discussions often focus on these; parents often being key in these discussions)
While seller-centric, we have also encountered sellers who want to have “one last holiday” in their home before putting it on the market.
Thinking about selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
Tax: Tax treatment depends on your individual circumstances and changes over time. Consult a CPA or tax professional about your situation.
As I'm Looking at Retirement, How Do I Access the Equity in My Home?
For many homeowners, the home is the largest asset they own. Here are four ways to access that equity as you approach retirement, and what to ask before you choose.
Important: Before you take any action, always discuss your situation with your own professionals, such as your accountant, investment advisor, attorney, trustees, and any other advisors you work with. This post is general information only and is not advice for your situation.
The situation
For many homeowners, their home is the largest single asset they own. As they look forward to retirement, it raises a practical question:
How do you turn some of that equity into income or flexibility without giving up more than you intend?
There are several routes to consider and you should consider all of them carefully before moving forward. To see how much of your overall wealth is tied up in your home, read How Much of Your Wealth Is in Your Home?
Option 1: Sell and move to a smaller or less expensive home
Selling frees the most equity. You can buy a smaller home, buy in an area that is “further out” and lower cost, or rent.
For many this is doable because they no longer need to commute to an office and the time that that takes out of their day.
On the down-side, costs include selling and moving expenses and, depending on your situation, taxes on the gain from the sale. Generally, up to $250,000 of profit ($500,000 for married couples filing jointly) can be excluded if you meet the ownership and use rules. Check with a CPA.
How the home sale exclusion works (example for illustration only, not tax advice). Taxable gain is generally the sale price, less selling costs, less what you paid for the home and spent on capital improvements, less the exclusion. The exclusion generally requires that you owned the home and lived in it as your main home for at least 2 of the last 5 years. Check IRS Publication 523 and talk with a CPA. If you are timing a sale around your plans, see When Should I Sell My Home? If you want to buy your next home before this one sells, see I Found a Home I Love for Retirement, but I Don't Know if Mine Will Sell.
| Sale price | Selling costs | Purchase price and capital improvements | Exclusion | Potential taxable gain |
|---|---|---|---|---|
| $1,500,000 | − $90,000 | − $700,000 | − $500,000 (married, filing jointly) | = $210,000 |
Option 2: Sell and rent
The up side:
- Renting avoids maintenance and ownership costs and keeps proceeds invested or available.
- If you are still working you can rent near your place of employment in the interim before you’re ready to buy.
The down side
- Rents can rise and you’ll need to accommodate this in your planning.
- You remove the opportunity for equity growth if the market goes up.
Our caution
We’ve heard from many potential sellers who are trying to “time the market.” While this does work out from time to time, it is not something we recommend unless you have very specific needs.
If you are considering this we highly recommend that you reach out to us and we can help you through your decision, identifying the pros and cons so you can make an informed decision.
Option 3: Stay and borrow against the home
For those that don’t want to leave where they live now, there are options. These generally allow you to be able to participate in any equity appreciation.
| Option | How it works | Pros | Cons |
|---|---|---|---|
| Cash-out refinance | Replaces your current mortgage with a larger one, and you take the difference in cash. | One monthly payment. Can be a fixed rate. Large lump sum. | Gives up your current rate, which is a real cost if it is low. Closing costs. Larger balance. You must qualify on income and credit. |
| Home equity line of credit (HELOC) | A revolving line with a variable rate. You draw what you need. | Borrow only what you need. Interest on what you draw. Keeps your existing mortgage. | Variable rate. The lender can reduce or freeze the line. Qualifying can be harder in retirement. Your home is collateral. |
| Home equity loan | A lump sum with a fixed payment, on top of your existing mortgage. | Fixed rate and payment. Keeps your existing mortgage. | A second monthly payment. Closing costs. Qualifying can be harder in retirement. Your home is collateral. |
| Reverse mortgage | Generally for homeowners 62 and older. You receive funds without monthly mortgage payments, and the loan is repaid when you move out or pass away. | No monthly mortgage payment. You stay in the home. | Costs and fees. The balance grows over time. You still pay taxes, insurance and upkeep. Less equity left for heirs. Federally insured versions require counseling with an approved counselor. Rules and limits change; see the HUD and CFPB links in this post. |
As always, we are available to help you through this thought process to find the right strategy and balance for you.
Option 4: Stay but earn from the home to offset costs
Renting a room or an accessory unit can add income, subject to local rules, zoning, permits and your insurance.
It is not unusual for people to utilize the extra space that empty nesters have to help offset other expenses. Consider family (children, parents, relatives), family friends, etc. This is especially beneficial if you are planning to purchase a home elsewhere but want to keep a “landing pad” in your current neighborhood until you’re ready to sell.
Questions to ask before you choose
- How long do I want to stay in this home, and what does aging in place require?
- How much income do I need, and for how long?
- What happens to the loan or the sale proceeds if my health or plans change?
- What are the tax effects, and how does this affect any benefits I receive?
- What do I want to leave to my family?
What not to do
- Do not borrow against the home to cover ongoing spending without a plan for repayment.
- Do not sign anything you do not understand, and be cautious with unsolicited offers.
- Do not decide in a rush. Get a net sheet and talk with a financial advisor and CPA first.
Want to investigate on your own? These are good places to start:
What others in our area are doing
In our experience, we have seen variations on all of these potential solutions. Each one has positives and negatives. We’ve seen and talked with clients who didn’t understand some of these, and eventually decided to move forward with ones they dismissed previously. Please consider each of them carefully; even if you think they are not the right ones they might actually be.
From Our Own Experience
A long time family friend is currently planning to move to a warmer climate for retirement. Their home holds a lot of equity, and they're looking to get a certain amount of that at the sale. Through great planning they were able to afford to purchase their second home, plus their primary home is already paid off, giving them options since they are in a good position to keep their primary home with an adult child living there until the home sells.
Whether or not the home sells at their target price, they have a great plan in place until it does:
- The rent the child pays helps offset utilities and taxes
- Someone is living within the home, which reduces the possibility of catastrophic issues going unnoticed (e.g., water leaks, frozen pipes, etc.)
- They can come back and visit (there are grandchildren in the area) in a comfortable, known location
While the future is unknown for all of us, these clients are set up for whichever way things go.
Every situation is different and we’re here to help walk you through the options.
Thinking about selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
Financial: Financing terms, rates and eligibility vary by lender and borrower. Talk with a lender or financial advisor before making decisions.
Tax: Tax treatment depends on your individual circumstances and changes over time. Consult a CPA or tax professional about your situation.
What Do Sellers Overlook Before Listing? A Short Guide
Most sellers declutter and cut the grass. The items that cost money are the ones they stop noticing. Here are the five areas to check before you list.
Most sellers know to declutter and cut the grass. The items that cost them money are usually the ones they have stopped noticing: a downspout that empties against the foundation, a handful of small repairs, a room that photographs badly. Buyers and their inspectors see these things in the first fifteen minutes.
This guide groups the most common overlooked items into five areas. Each area has its own post with the details, what to do and what not to do.
The five areas
| Area | What is in it | Why it matters | Read more |
|---|---|---|---|
| 1. Water and moisture | Moisture and drainage, attic and crawl space, trees and plants near the house | Water is what inspectors and buyers worry about most. | Read the post |
| 2. Small problems | Deferred maintenance, safety items, roof, exterior, decks and porches | Small problems add up and read as neglect. | Read the post |
| 3. Presentation | Lighting, the photo test, deep cleaning and odors, decluttering, paint and flooring, curb appeal | Buyers see the photos before they see the house. | Read the post |
| 4. Paperwork and records | Service records, documents to gather, permits | Good records support your price and avoid delays. | Read the post |
| 5. Logistics and planning | Show-readiness, where you will live and store things, contractor lead times, an outside opinion, avoiding over-improving | Timing and planning decide how smoothly the sale goes. | Read the post |
If you only do five things
- Find and fix the source of any moisture or drainage problem.
- Walk through the house and finish the small repairs.
- Deep clean, clear out and fix the lighting.
- Gather your service records and documents.
- Make the home easy to show on short notice.
Start with water. Water problems are the ones most likely to turn into a negotiation after the inspection.
If something turns up, we can help
As agents we work with contractors and other vendors regularly, and we can share names from our experience and help you compare bids. You always choose who to hire. A broker should not require you to use their vendor, and should not be paid by a vendor you hire.
Thinking about buying or selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.
How Much of Your Wealth Is in Your Home?
For many homeowners, the home is the biggest piece of their wealth. Here are the national numbers, how Eastside home values compare with incomes, and what that means for your plans.
The national picture
- For households that own a home, housing is typically the largest share of their assets. One analysis of the Federal Reserve's 2019 Survey of Consumer Finances found that homeowners held a typical 61 percent of total assets in housing (Economic Policy Institute).
- The share falls as wealth rises. A Redfin analysis published in March 2025 found real estate made up about 46 percent of net worth for the bottom half of U.S. households and about 12 percent for the top 1 percent.
- Housing wealth grew during the pandemic years. The Federal Reserve's 2022 survey reported that for families who own their primary residence, housing wealth rose substantially between 2019 and 2022 as house prices far outpaced inflation.
Why there is no single local number
The Federal Reserve survey does not publish a figure for the Seattle area. What we can do is compare what homes cost with what households earn, nationally and in the cities we serve.
Prices and incomes: national and local
| Area | Median household income | Median home value | Home value ÷ income |
|---|---|---|---|
| United States | $80,734 | $332,700 | 4.1 |
| Snoqualmie | $214,107 | $977,200 | 4.6 |
| Maple Valley | $152,885 | $724,700 | 4.7 |
| Sammamish | $239,690 | $1,407,300 | 5.9 |
| North Bend | $175,109 | $1,048,600 | 6.0 |
| Issaquah | $154,669 | $963,000 | 6.2 |
| Renton | $100,432 | $672,600 | 6.7 |
| Redmond | $162,560 | $1,167,800 | 7.2 |
| Bellevue | $165,576 | $1,340,300 | 8.1 |
Source: U.S. Census Bureau QuickFacts, American Community Survey 5-year estimates, 2020-2024. Home value is the owner-reported median value of owner-occupied housing units, not a sale price. Ratio is median home value divided by median household income.
For scale: dividing median home value by median household income gives about 4.1 for the United States. Using the same Census measure, the ratio is about 4.6 in Snoqualmie, 4.7 in Maple Valley, 5.9 in Sammamish, 6.0 in North Bend, 6.2 in Issaquah, 6.7 in Renton, 7.2 in Redmond and 8.1 in Bellevue. Home value is the owner-reported estimate, not a sale price, so treat these as rough comparisons.
Equity gains in our market
- Using Northwest MLS data for King County (via InfoSparks), the average of the monthly median sales prices for residential homes rose from about $671,000 in 2019 to about $895,000 in 2022, a gain of roughly 34 percent. For condominiums, it rose from about $405,000 to about $498,000, roughly 23 percent. Measured from the end of 2019 to the 2022 peak, the gain was larger: residential homes went from $675,000 in December 2019 to $1,000,000 in May 2022 (about 48 percent), and condominiums from $405,000 to $549,950 in March 2022 (about 36 percent). Prices have since come down from those peaks.
- Prices have softened recently. See our post on how local home values are doing.
Why this matters
When a large share of your wealth is in one asset, in one place, the value of that asset matters a great deal to your plans. Many homeowners find that a home with a lot of equity gives them choices, such as selling, downsizing or borrowing, and also concentrates risk. Reviewing how much of your wealth is tied up in your home is a reasonable part of retirement and estate planning.
Related reading: As I'm Looking at Retirement, How Do I Access the Equity in My Home?
Sources
- Economic Policy Institute, from the Federal Reserve Survey of Consumer Finances 2019: epi.org/chart/kyle-and-adewale-figure-a-americans-homeowners-hold-most-of-their-assets-in-their-primary-residence-this-is-especially-true-for-black-and-brown-households
- Redfin, March 2025: businesswire.com/news/home/20250311763660/en/Americas-Wealthiest-1-Could-Buy-99-of-Americas-Homes
- Federal Reserve Survey of Consumer Finances 2022, as reported by Anadolu Agency: aa.com.tr/en/americas/americans-net-worth-soar-record-37-during-2019-2022-fed/3026392
- Census Bureau QuickFacts, American Community Survey 5-year estimates, 2020-2024: census.gov/quickfacts
- Northwest MLS via InfoSparks, King County median sales price, 2019 to 2022 (annual averages of monthly medians)
From Our Own Experience
We are noticing a trend that many people in our area are looking at homes where they can eventually settle in retirement while keeping their Seattle-area residences. Unlike many metropolitan areas, Seattle has been blessed with success over the last 30+ years largely due to the tech industry. As people decide to leave (or are laid off) the area, they are looking to cash in on their equity and redeploy it.
Thinking about selling in the Seattle Area?
Kelly Azzarello Real Estate | Compass
Email: kelly@kellyazzarello.com
Phone: (425) 830-6457
Web: www.kellyazzarello.com
Instagram: instagram.com/kellyazzarello
YouTube: youtube.com/kellyazzarellorealestate
This post is general information about real estate topics. It is not legal, tax or financial advice, and it does not replace a professional inspection. Rules and practices differ by situation and change over time. Check current requirements and talk with a licensed professional, such as an inspector, contractor, attorney or CPA, about your own property.